Introduction
Taking a gold loan from a bank or non-banking financial company (NBFC) is a quick way to manage sudden financial needs. However, as interest rates compound and monthly tenure ends, servicing the debt can become a heavy financial burden.
If you are struggling with high interest payments or need liquidity, you don’t have to forfeit your jewellery. You can release your pledged gold, clear the loan completely, and keep the leftover cash value.
Why Release Your Pledged Gold?
- Stop Interest Accumulation: Avoid compound interest charges, penalties, and auction risks if you miss repayment deadlines.
- Unlock Lost Equity: Gold prices appreciate over time. The market value of your pledged gold is often significantly higher than the outstanding loan amount you owe.
- Immediate Extra Cash: Once the loan is settled, the difference between the gold's current value and the debt is handed directly to you in cash or bank transfer.
Step-by-Step Guide: How the Release Process Works
Step 1: Request a Loan Settlement Statement
Visit your lending bank or financial institution and ask for an official closure balance statement. This document shows the exact amount required (principal + accrued interest) to clear your loan account.
Step 2: Evaluation & Offsite Assistance
A trusted gold buyer evaluates your loan documents and calculates the live market value of the pledged gold. If the gold’s current value exceeds your loan balance, the buyer agrees to pay off your debt on your behalf.
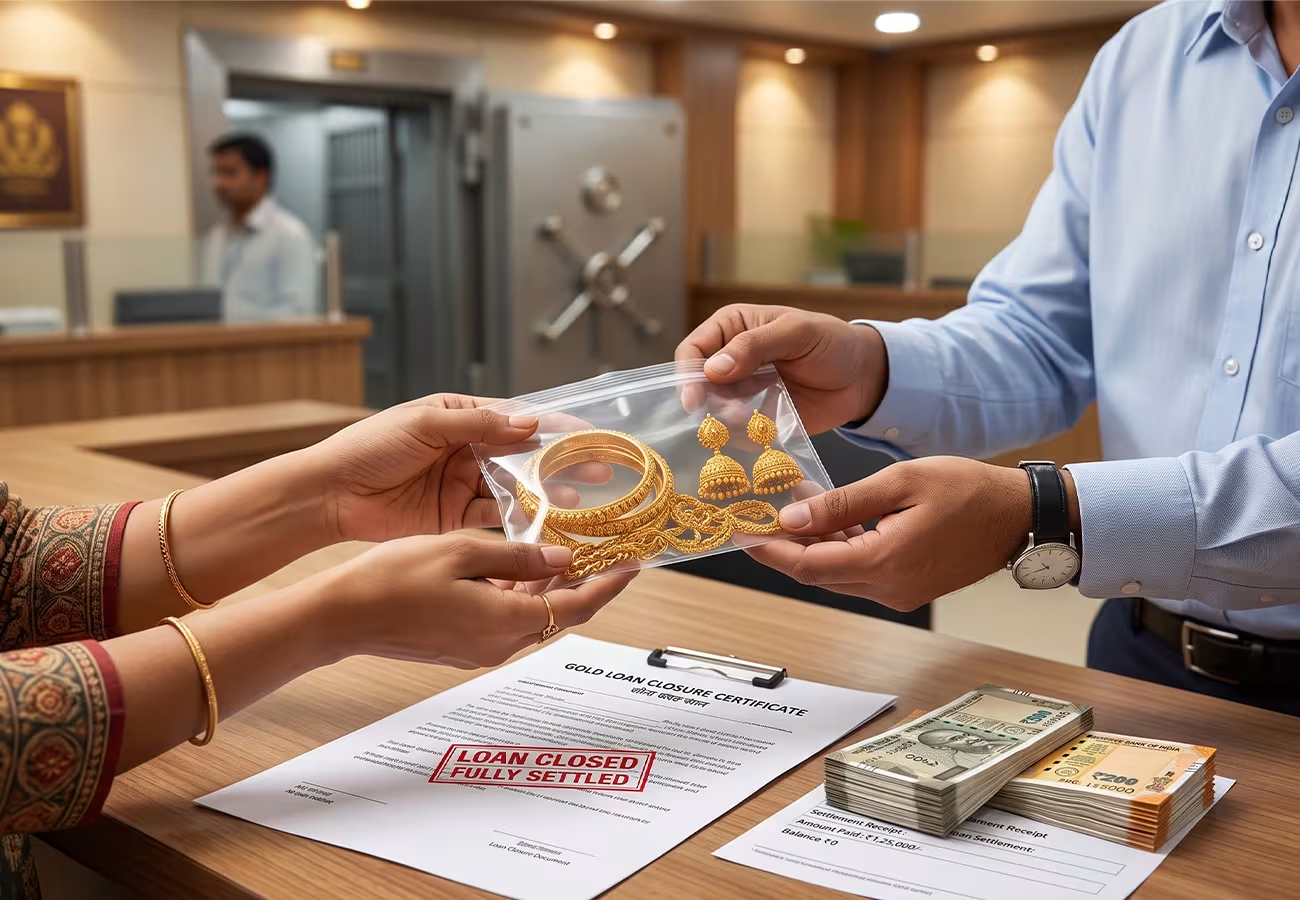
Step 3: Bank Settlement & Gold Retrieval
A trusted gold buyer evaluates your loan documents and calculates the live market value of the pledged gold. If the gold’s current value exceeds your loan balance, the buyer agrees to pay off your debt on your behalf.
Step 4: Final Purity Check & Instant Payout
The retrieved gold is taken to the buyer’s branch for a precise, non-destructive XRF purity check in your presence. The buyer deducts the loan amount previously paid to the bank and transfers the remaining profit balance directly to your account.
Key Precautions When Settling Pledged Gold Loans
- Verify Ownership Credentials: Lenders will only release pledged gold to the original loan applicant with valid government ID proofs (Aadhaar, PAN) and original pledge receipts.
- Beware of Excessive Service Fees: Work only with buyers who charge a clear, upfront processing fee rather than hidden deductions on the final payout.
- Insist on On-the-Spot Payment: Ensure the remaining balance is transferred via IMPS/NEFT or cash immediately upon retrieving and testing the metal.
Conclusion
Pledged gold doesn’t have to remain locked away while interest costs stack up. Settling your gold loan with a transparent local buyer allows you to clear debt stress-free while securing the surplus cash value your gold holds today.